About 2.7 million homeowners are behind on their mortgage payments and 1.8 million are seriously delinquent 90 days or more past due or are in foreclosure. 77% of homeowners in forbearance programs have a loss mitigation repayment plan in place according to the Mortgage Bankers Association. With the rapid level of home price appreciation in the last year many distressed owners will be able to avoid foreclosure by selling or refinancing. Homes backed by FHA mortgages are most at risk and have the highest delinquency rates. FHA Loans require minimal down payments and underwriting is considerably more forgiving than conventional loans. There are ten metro areas identified with the highest risk of foreclosures and none of those Metro areas are in Florida. The following Metro are at the highest risk:
Atlanta
Houston
Chicago
Dallas
Washington-Arlington-Alexandria, D.C.-Virginia-Maryland-West Virginia
Baltimore
Riverside-San Bernadino
San Antonio
Fort Worth
Phidelphia
To put this in perspective on the National scale, there’s currently a shortage of 5 million single family homes in the United States compared to 1.8 million seriously delinquent mortgages.
Given the recent home price appreciation and all the given forbearance / refinance options available the most likely scenario is that about one-third of these delinquent loans could end up on the market or in foreclosure. That’s about 618,000 homes which equates to 1.3 months of supply of the current monthly sales pace of 480,333. This modest increase in supply would temper home price appreciation a bit but the overall impact will be minimal.
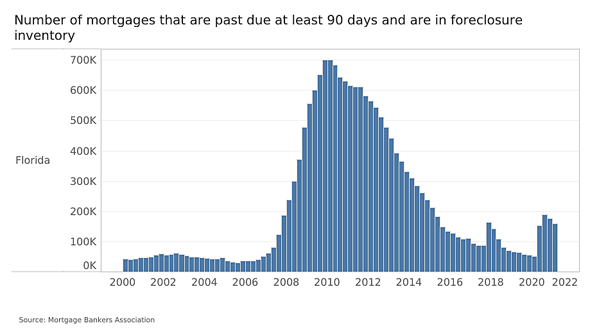
And if you’ve heard about a massive wave of foreclosures coming, take a look at this chart for the State of Florida. Note the number of mortgages 90 days past due in 2010 compared to now.
Todays Mortgage Rates
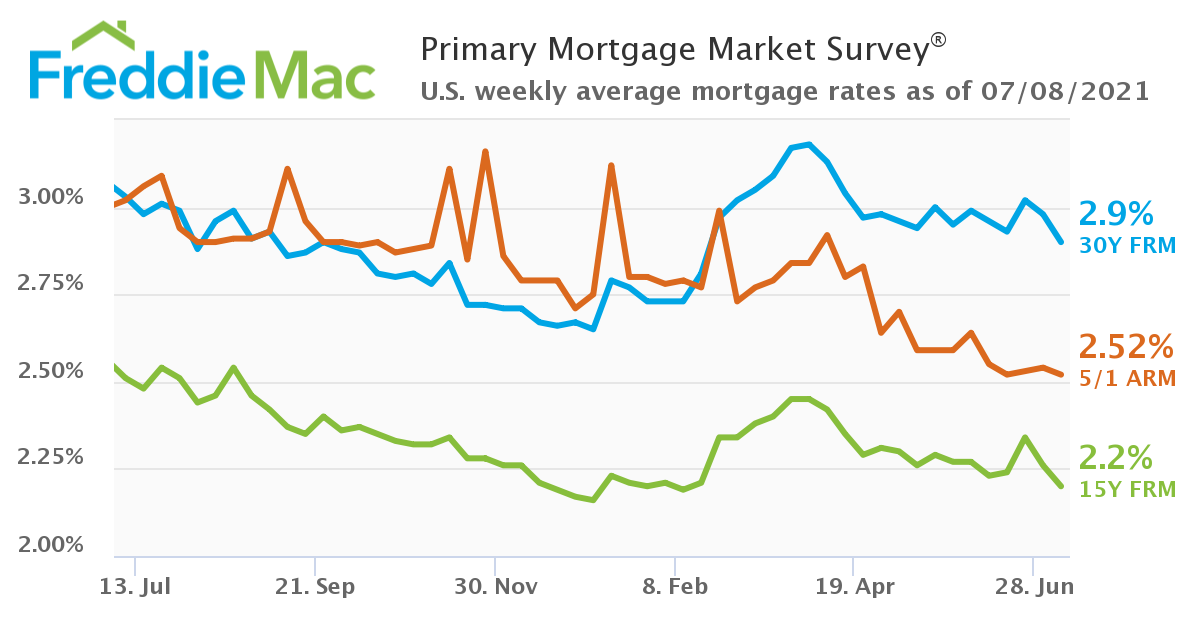
Mortgage Rates Continue to Move Down July 8, 2021
Mortgage rates decreased this week following the dip in U.S. Treasury yields. While mortgage rates tend to follow Treasury yields closely, other factors can be impactful such as the labor markets, which are continuing to improve per last week’s jobs report. We expect economic growth to gradually drive interest rates higher, but homebuyers and refinance borrowers still have an opportunity to take advantage of 30-year rates that are expected to continue to hover around three percent.