The 2008 financial crisis was caused, in part, by mortgage lenders taking on too much risk. Now, the pendulum has swung so far in the opposite direction that the private sector has all but ceased taking on mortgage risk any more.
Bank capital and liquidity rules implemented after the 2008 financial crisis make mortgage lending and servicing unattractive to banks trying to maximize their return on capital — especially once compliance costs are added in. “It is becoming increasingly difficult for banks to stay in the mortgage business, which ultimately hurts everyday Americans,” wrote JPMorgan CEO Jamie Dimon in this year’s shareholder letter.
Nonbanks now originate 71% of agency-backed loans and 86% of government-backed loans. The mortgage market is now dominated by nonbanks that operate with relatively thin cushions of capital and need substantial economies of scale.
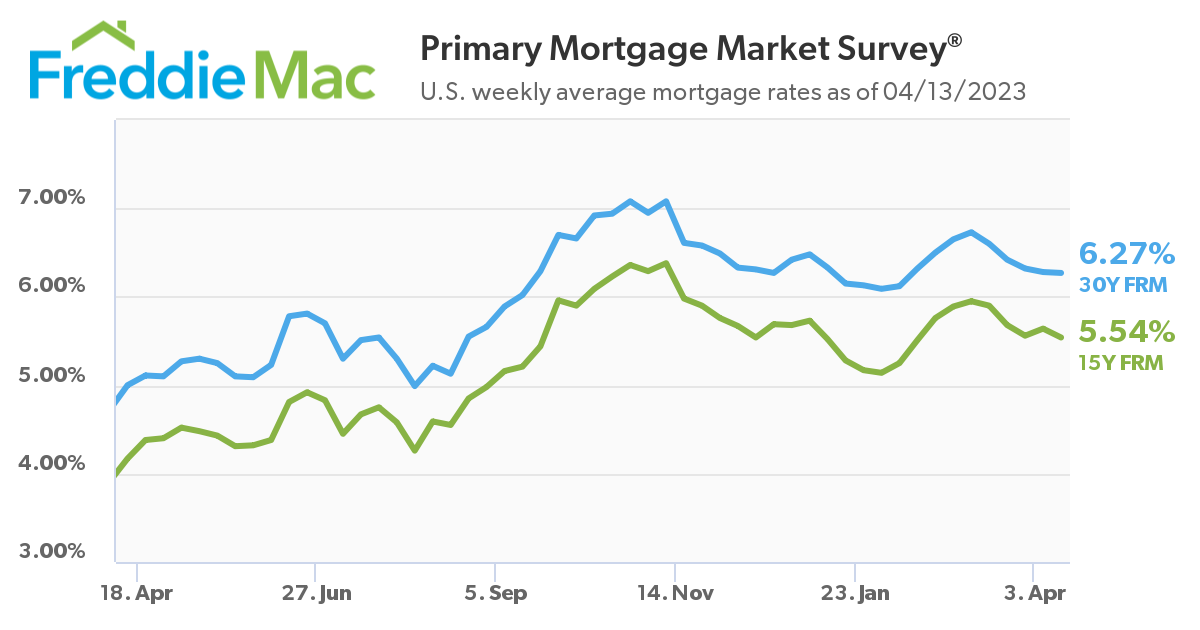
Mortgage rates decreased for the fifth consecutive week. Incoming data suggest inflation remains well above the desired level but showing signs of deceleration. These trends, coupled with tight labor markets, are creating increased optimism among prospective homebuyers as the housing market hits its peak in the spring and summer.