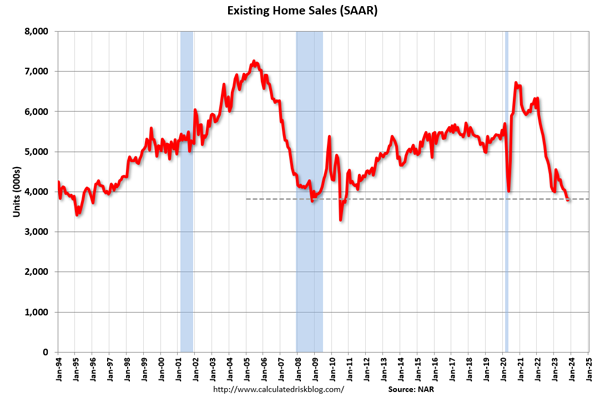
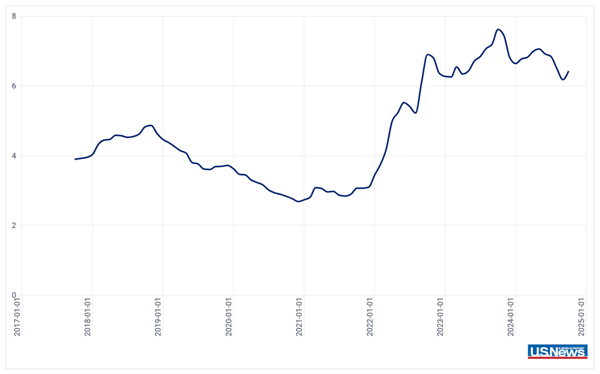
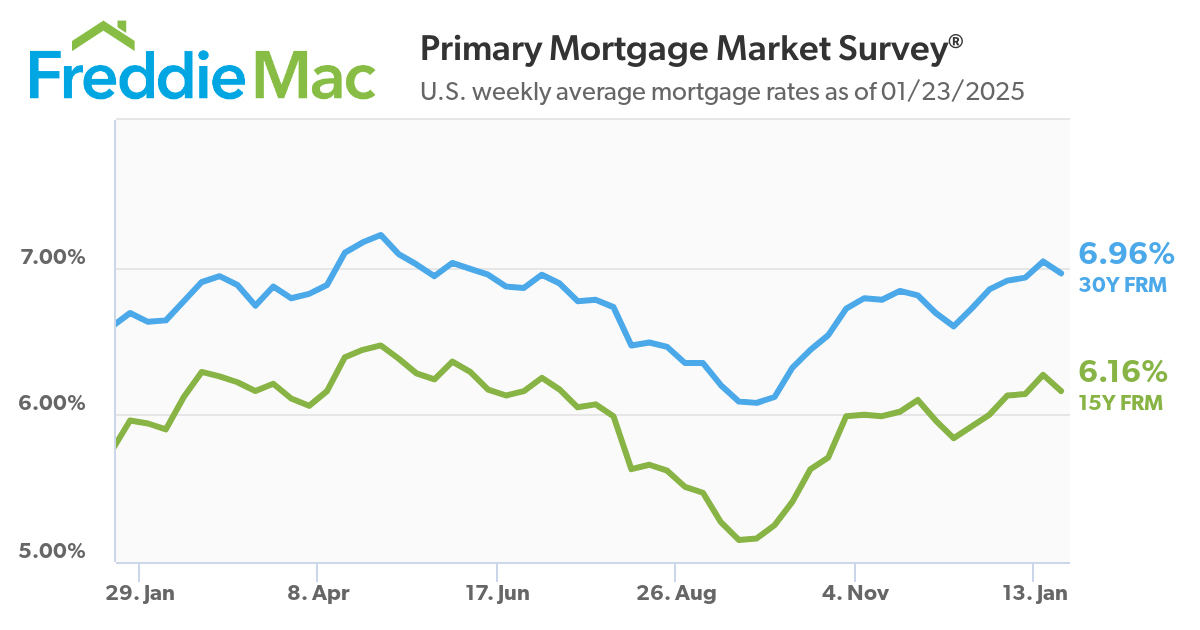
In comparison with historical norms prior to the pandemic years, home sales are expected to remain low as long as mortgage rates remain well over the 6% level. According to recent projections, the Federal Reserve doesn’t see inflation subsiding to 2.0% on a consistent basis until early 2026. This will mean higher but gradually declining short-term interest rates throughout 2025.
With rising costs for property taxes, home insurance, maintenance, the total costs for homeownership are far more than just mortgage principal and interest payments alone. According to a study in mid-2024 by Bankrate, these annual variable costs for a typical single-family home rose by nearly 26% between March 2020 and March 2024.
After crossing the 7%-mark last week, the 30-year fixed-rate mortgage saw its first decline in six weeks. While affordability challenges remain, this is welcome news for potential homebuyers, as reflected in a corresponding uptick in purchase applications.