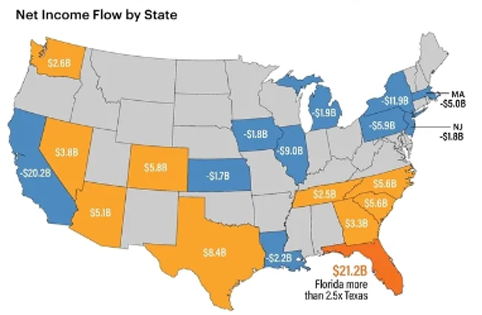
Florida’s real estate market has changed significantly in the past few years. Mortgage rates have added to monthly costs. Insurance and property taxes are weighing more heavily on household budgets. At the same time, people, income, businesses and investment continue to flow into the state. Even as overall migration to Florida has slowed from recent peaks, the state continues to attract more net household income through domestic migration than any other state – about $21.2 billion annually. A significant part of that movement is coming from households ages 55–64. This group accounts for the largest share of Florida’s net income migration and often includes people who are still in their peak earning years, have accumulated home equity and may be considering a relocation home, second home or next-stage lifestyle move.
Florida also is becoming a more mature and economically diverse market. The report notes that the state is transitioning from a lower-cost growth market toward a higher-income and more diversified economic environment.
Those fundamentals are helping support housing demand, but affordability remains one of the biggest challenges facing buyers.
Source: Florida REALTORS Economist Report
This report is very comprehensive.
If you want to dig further click the linkto see the entire report
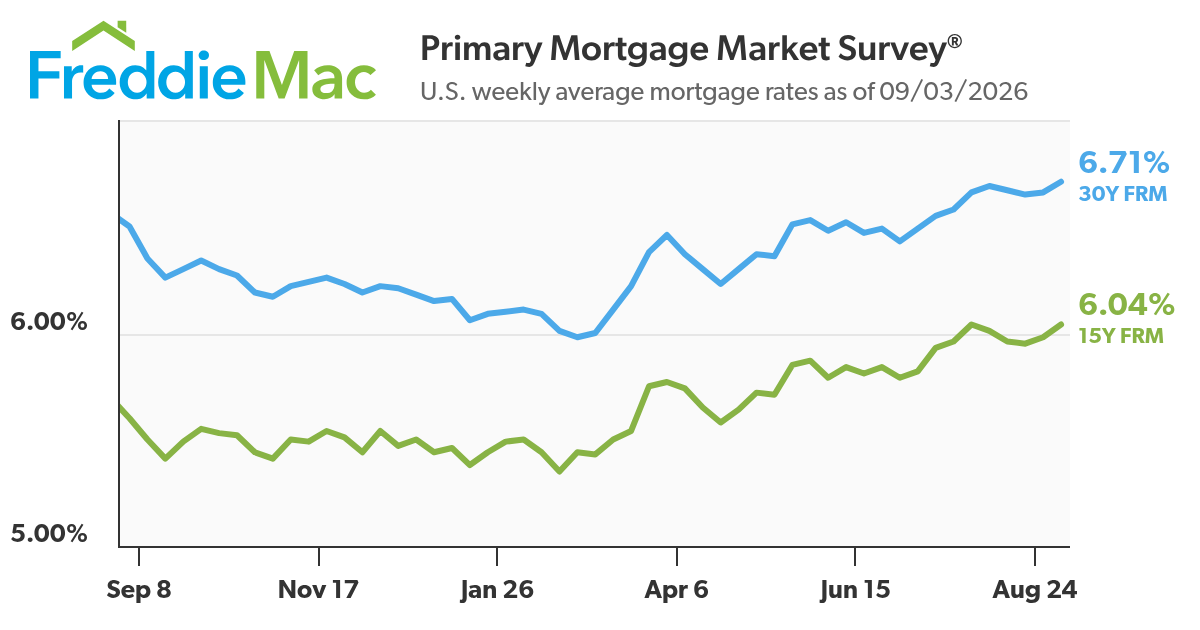
The 30-year fixed-rate mortgage averaged 6.71% this week. Purchase demand has remained relatively stable indicating steady interest from buyers adapting to evolving market conditions.
The 30-year fixed-rate mortgage averaged 6.71% as of September 3, 2026, up from last week when it averaged 6.66%. A year ago at this time, the 30-year FRM averaged 6.50%.
The 15-year fixed-rate mortgage averaged 6.04%, up from last week when it averaged 5.98%. A year ago at this time, the 15-year FRM averaged 5.60%.